-
Shop
- Advanced Technologies
- Beauty
- Best-Sellers
- Car Accessories
- Dating & Social Skills
- Digital Resources
- AI & Technology
- AI Skills
- Car Buying & Ownership
- Cozy Feast Collection
- Electronics & Technology
- Emotional Intelligence
- Financial Education
- Hobbies
- Home Styling & Organization
- Kitchen & Recipes
- Mindfulness
- Mindset
- Online Business
- Parenting & Child Development
- Pet Lifestyle & Wellness
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Wealth
- Wealth Building
- Budgeting & Saving
- Cryptocurrency Investing
- Debt Management
- Entrepreneurship & Business Growth
- Family Finance & Budgeting
- Financial Independence
- Financial Mindset & Psychology
- Financial Planning
- Frugal Living & Expense Hacks
- Goal Setting
- High-Income Skills
- Investing Basics
- Leadership
- Motivation
- Networking & Mentorship
- Passive Income Strategies
- Real Estate Investing
- Side Hustles
- Stock Market Investing
- Wellness
- Popular
- Best deals
Budget Spreadsheet Checklist: Simple Plan, Track, Repeat
Ultimate Budget Spreadsheet Checklist: Build a Simple System That Runs Your Money
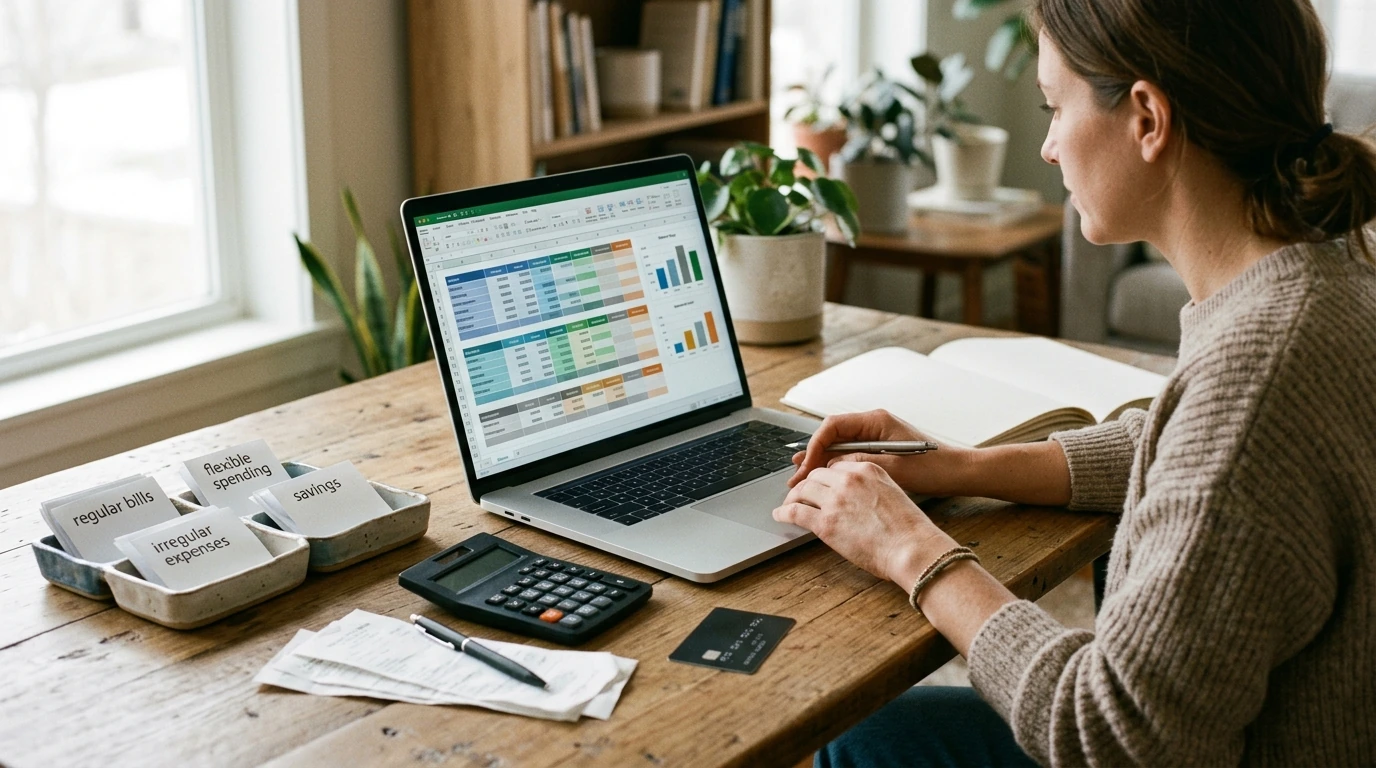
A budget works best when it’s clear, repeatable, and easy to maintain. A checklist-style spreadsheet helps turn income, bills, and goals into a simple routine you can update in minutes—so day-to-day spending decisions feel calmer, and progress is visible without complicated tools.
What a budget spreadsheet should do (and what it should never do)
A strong budget spreadsheet acts like a reliable dashboard, not a detailed diary. The goal is clarity you can sustain, even on busy weeks.
- Show one trustworthy snapshot: income, fixed bills, variable spending, savings, and debt in one place.
- Separate planning from tracking: plan the month first, then compare plan vs. actual in a quick weekly check-in.
- Make trade-offs obvious: if dining out rises, another category drops (or savings changes) on purpose.
- Stay lightweight: fewer categories beats endless micro-categories that never get updated.
- Support real life: include irregular expenses (annual fees, car repairs, gifts) so they don’t “surprise” your budget.
Pre-work checklist: gather numbers before opening the spreadsheet
Most budget “fails” happen before the spreadsheet is built—usually because key numbers are missing. Do this quick prep first so your plan reflects reality.
- List all income sources with pay dates (salary, freelance, benefits, side gigs).
- Pull the last 2–3 months of bank and card statements to spot your typical spending patterns.
- Write down every fixed monthly bill (rent/mortgage, insurance, subscriptions, debt minimums).
- Identify irregular expenses and assign a monthly sinking-fund amount (for example, annual renewals ÷ 12).
- Decide the budget period: monthly planning works best for most households, with weekly check-ins for control.
If you’re unsure where to start, the Consumer Financial Protection Bureau (CFPB) budgeting resources offer practical guidance on building a plan around real expenses.
Build the spreadsheet: tabs, columns, and formulas that keep it clean
A clean structure prevents the common spiral of messy categories and missing transactions. A three-tab setup stays simple while still showing what matters.
- Create 3 core tabs: (1) Budget Plan, (2) Actual Spending, (3) Summary Dashboard.
- Budget Plan tab: categories down the left; columns for Planned, Actual, Difference, Notes.
- Actual Spending tab: log date, merchant, category, amount, and payment method; use a dropdown for categories.
- Summary tab: totals by category, savings rate, debt payoff progress, and month-end balance.
- Use simple formulas: SUM for totals, Planned-Actual for variance, and conditional formatting for overspending.
- Add guardrails: protect formula cells, freeze header rows, and keep category names identical across tabs.
For extra confidence in your income estimates (especially if you’re adjusting withholding), the IRS Tax Withholding Estimator can help you avoid unpleasant surprises.
A practical category framework that won’t collapse mid-month
Categories should guide decisions, not create homework. A smaller set of categories makes it easier to see what’s driving the month.
- Start with 8–12 categories, then expand only if decisions aren’t clear.
- Separate essentials from flex: housing, utilities, groceries, transport vs. dining, fun, shopping.
- Include “Financial Goals” as a category group: emergency fund, retirement, sinking funds, and extra debt payments.
- Use one “Buffer/Misc” line to absorb small surprises without breaking the plan.
- If income varies, budget from the minimum expected income and treat extra income as a deliberate choice (save, pay debt, or a planned splurge).
Example monthly budget layout (starter categories)
| Category | Planned ($) | Actual ($) | Difference ($) | Notes |
|---|---|---|---|---|
| Income (total) | — | — | — | List sources and pay dates |
| Housing | 1200 | — | — | Rent/mortgage, HOA |
| Utilities | 180 | — | — | Electric, gas, water, internet |
| Groceries | 450 | — | — | Household food and basics |
| Transportation | 220 | — | — | Fuel, transit, parking |
| Insurance | 160 | — | — | Health/auto/renters |
| Debt minimums | 300 | — | — | Loans/credit cards |
| Savings & sinking funds | 250 | — | — | Emergency + irregular expenses |
| Dining & entertainment | 150 | — | — | Meals out, streaming, events |
| Buffer/Misc | 75 | — | — | Small surprises |
Weekly money routine: a 15-minute cadence that keeps you on track
Consistency beats intensity. A short weekly review prevents end-of-month panic and keeps trade-offs intentional.
- Pick a consistent day/time for a quick review (Sunday evening works well for many households).
- Import or log transactions and confirm categories match the plan.
- Check variance: focus on the 2–3 categories with the biggest overspend first.
- Make one mid-month adjustment: move money intentionally rather than hoping it works out.
- End-of-month closeout: reconcile totals, record lessons learned, and copy the template for next month.
If you want a straightforward checklist approach to money habits, the Federal Trade Commission’s guidance on managing your money is a helpful reference for staying organized and avoiding common financial missteps.
Common spreadsheet pitfalls and quick fixes
Ready-to-use checklist and template option
- Ultimate Budget Spreadsheet Checklist: Master Your Money Like a Pro (Digital Download)
- The Ultimate Employee Motivation Checklist (Printable PDF Download)
- Understanding Attachment Theory for Parents (Digital Download)
FAQ
What’s the simplest budget spreadsheet setup for beginners?
Use three tabs (Plan, Actual, Summary), stick to 8–12 categories, and include Planned/Actual/Difference columns. A weekly check-in is enough for most households to stay accurate without feeling constant.
How do sinking funds work in a spreadsheet?
List irregular expenses (like annual subscriptions or car maintenance), divide each by 12, and budget that monthly amount under “Savings & sinking funds.” Track the running balance so those bills are already funded when they hit.
How often should a budget spreadsheet be updated?
Weekly updates work best for most people, plus a month-end closeout to reset and learn. Daily updates are only necessary when spending is highly variable or short-term goals require tighter control.




Leave a comment