-
Shop
- Advanced Technologies
- Beauty
- Best-Sellers
- Car Accessories
- Dating & Social Skills
- Digital Resources
- AI & Technology
- AI Skills
- Car Buying & Ownership
- Cozy Feast Collection
- Electronics & Technology
- Emotional Intelligence
- Financial Education
- Hobbies
- Home Styling & Organization
- Kitchen & Recipes
- Mindfulness
- Mindset
- Online Business
- Parenting & Child Development
- Pet Lifestyle & Wellness
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Wealth
- Wealth Building
- Budgeting & Saving
- Cryptocurrency Investing
- Debt Management
- Entrepreneurship & Business Growth
- Family Finance & Budgeting
- Financial Independence
- Financial Mindset & Psychology
- Financial Planning
- Frugal Living & Expense Hacks
- Goal Setting
- High-Income Skills
- Investing Basics
- Leadership
- Motivation
- Networking & Mentorship
- Passive Income Strategies
- Real Estate Investing
- Side Hustles
- Stock Market Investing
- Wellness
- Popular
- Best deals
A Biweekly Payday Routine for Steady Savings
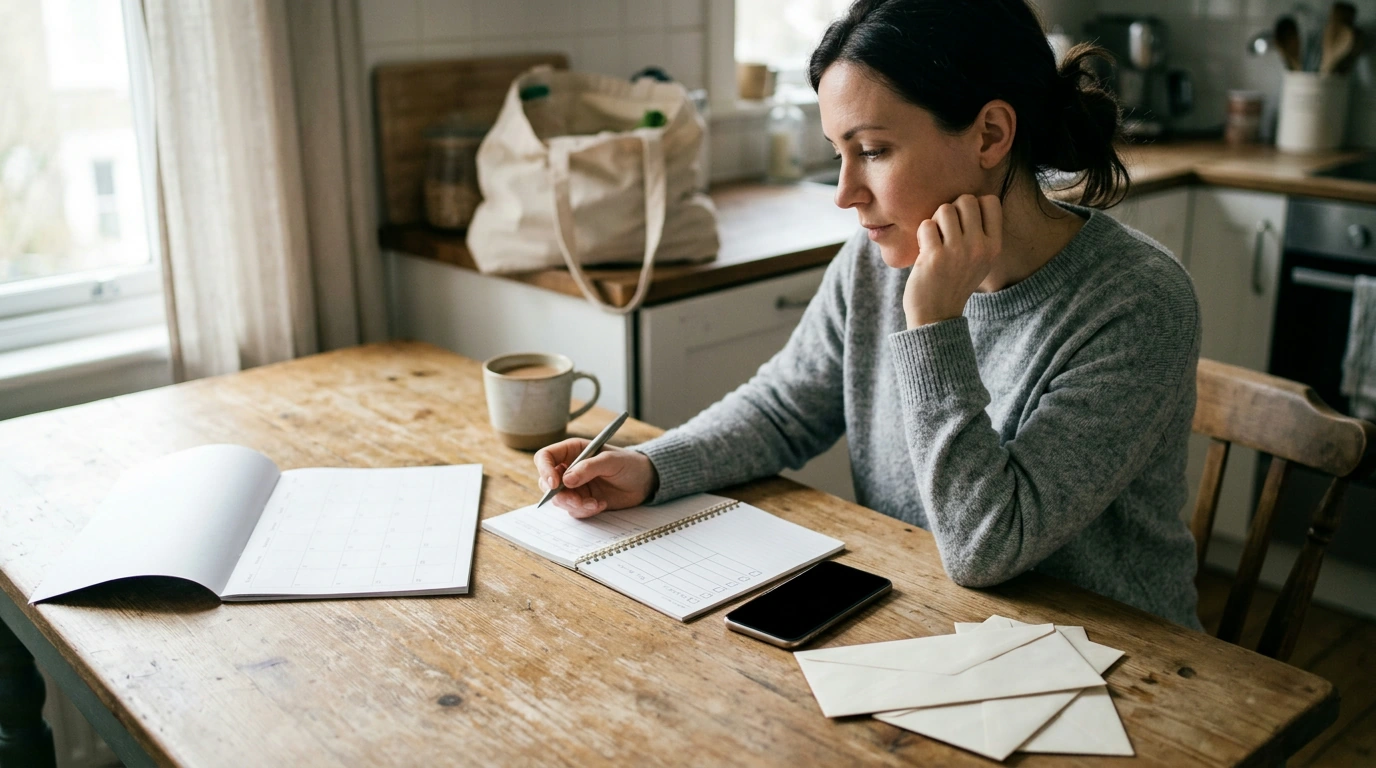
Saving money can feel more manageable when the next step is small and tied to a day already on your calendar. If you’re paid every two weeks, payday can be your cue to see what’s coming in, cover what’s due, and decide whether you can move something toward a goal. You don’t need to save the same amount every time. You need a decision that works for this paycheck.
Start with the money this paycheck needs to cover
Before choosing a savings amount, look at your take-home pay and current account balance. Then list the bills and essentials you’ll need to pay before the following payday. Include rent or mortgage payments, groceries, transportation, utilities, and minimum debt payments as they apply to you. The Consumer Financial Protection Bureau’s budgeting resources can help you organize income and expenses if you need a place to start.
Some costs won’t line up neatly with a two-week pay cycle. A monthly bill may fall just after your next paycheck, while an annual renewal or car repair can appear with little room in the current plan. Set aside what you reasonably can for these less frequent expenses before treating the remaining balance as available to save or spend.
Only then choose a savings amount. Moving $10 that stays in savings is more useful than moving $100 and needing it back for groceries three days later. If a transfer would put an essential payment at risk or leave you facing an overdraft, lower the amount or skip it this time.
Give each payday one small savings task
A savings transfer is easier to evaluate when you know what it’s for. You might be building an emergency cushion, replacing a worn-out appliance, or preparing for a planned purchase. Pick one priority for now and give the money a clear destination, such as a separate savings account.
On payday, decide what you can afford to move after reviewing upcoming expenses. You can transfer it then or schedule the transfer for a later date in the pay period if that gives bills more room to clear. If your income changes from paycheck to paycheck, make a fresh decision each time instead of assuming a fixed automatic transfer will always fit.
Here’s a quick check-in you can repeat:
| When | Action | Question to ask |
|---|---|---|
| Before payday | List bills and essentials due before the following paycheck. | What must this deposit cover? |
| On payday | Choose an affordable savings amount. | What can I move without putting essentials at risk? |
| Midway through the pay period | Check spending and upcoming payments. | Does anything need adjusting? |
| Before the next payday | Note what worked and what changed. | What is one improvement for next time? |
A tight pay period still calls for a check-in. If the affordable amount is zero, write that down, handle necessary expenses, and revisit the question on your next payday. The habit is checking and deciding—not forcing a transfer regardless of the numbers.
Make the routine easy to repeat
Keep your payday review short enough that you’ll actually do it: review the deposit and upcoming costs, decide whether to save, make or schedule a transfer if appropriate, and mark the check-in complete. A recurring calendar reminder can bring you back to the task without requiring you to remember which Friday comes next.
If you’d like one place to keep that habit in view, The Biweekly Money Boost Checklist is our digital download for a recurring payday routine. Use it as a prompt to make your own decision each pay period, not as a reason to commit to an amount your budget can’t support.
We also carry The Ultimate Employee Motivation Checklist for readers organizing a separate workplace routine. It isn’t a budgeting tool; for your personal savings check-in, keep the focus on pay, expenses, and your current goal.
If you’re building a budget alongside this habit, FDIC Money Smart offers consumer education resources on everyday money decisions. You can use those broader tools while keeping your payday task simple.
Review progress without starting over
After several pay periods, compare what you planned to save with what remained in savings. If you repeatedly need to move money back, that’s useful information: your savings target may be too high, or an irregular cost may need its own line in your plan. Adjust the next transfer instead of treating the earlier ones as failures.
Look for changes in bills, income, and priorities. A higher utility bill might call for a smaller transfer this month. If your emergency cushion has become more urgent than a planned purchase, you can redirect future savings without abandoning the payday routine.
Our team encourages you to notice consistency as well as the account balance. A thoughtful check-in during a difficult pay period helps you protect essentials and make a better choice next time. Every other payday is another opportunity to review what’s real today and take the small step that fits.
FAQ
How much should I save from each biweekly paycheck?
There is no universal amount. Cover bills and essentials first, then choose an amount you can keep in savings without relying on credit or risking an overdraft.
What if I cannot save anything this pay period?
Do the check-in anyway. Note what changed, prioritize necessary expenses, and revisit the savings amount on your next payday.
Recommended for you
Antony Morato Men’s Suede Moccasins: Style & Care
Oct 24, 2026



Leave a comment