-
Shop
- Advanced Technologies
- Beauty
- Best-Sellers
- Car Accessories
- Dating & Social Skills
- Digital Resources
- AI & Technology
- AI Skills
- Car Buying & Ownership
- Cozy Feast Collection
- Electronics & Technology
- Emotional Intelligence
- Financial Education
- Hobbies
- Home Styling & Organization
- Kitchen & Recipes
- Mindfulness
- Mindset
- Online Business
- Parenting & Child Development
- Pet Lifestyle & Wellness
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Wealth
- Wealth Building
- Budgeting & Saving
- Cryptocurrency Investing
- Debt Management
- Entrepreneurship & Business Growth
- Family Finance & Budgeting
- Financial Independence
- Financial Mindset & Psychology
- Financial Planning
- Frugal Living & Expense Hacks
- Goal Setting
- High-Income Skills
- Investing Basics
- Leadership
- Motivation
- Networking & Mentorship
- Passive Income Strategies
- Real Estate Investing
- Side Hustles
- Stock Market Investing
- Wellness
- Popular
- Best deals
Budget That Works: Worksheets, Sinking Funds, Weekly Check-Ins
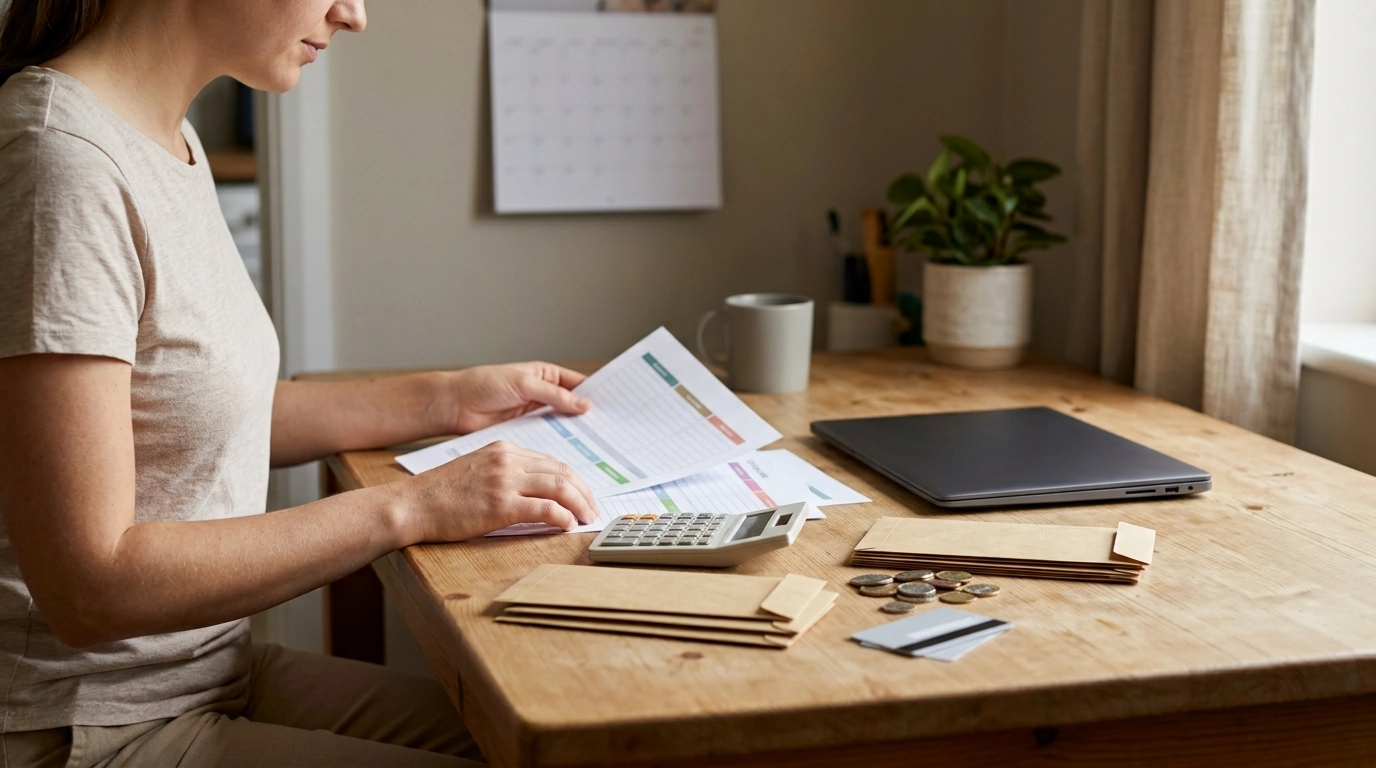
Master Your Money: A Budget That Actually Works (Worksheets + Real-Life Tips)
A budget “works” when it reflects how money actually moves through your life: bills that hit on odd days, expenses that show up quarterly, and weeks when willpower is lower than usual. The goal isn’t perfection—it’s a system you can repeat, adjust, and trust. Below is a practical way to set up a budget that feels clear, flexible, and consistent, plus worksheet habits that keep it running with minimal effort.
Start with the goal: clarity, control, and fewer surprises
Before you touch categories or percentages, decide what “working” means for you. For some people, it’s paying bills on time. For others, it’s saving consistently, reducing stress, or paying off debt without feeling trapped.
- Pick 1–3 measurable targets. Examples: build a $1,000 starter emergency fund, pay an extra $100/month toward debt, or save 10% for a trip.
- Set a realistic time horizon: run a 30-day plan first, then refine for 90 days once you see real patterns.
- Keep the first month simple—clarity beats complexity early on.
Gather the numbers that matter (without overcomplicating it)
Budgets break when they’re built on guesses. Start with what’s true right now.
- List take-home income sources (paychecks, gig work, benefits) and note whether income is steady or variable.
- Review the last 1–3 months of statements to capture your real spending—including small recurring charges that quietly add up.
- Sort expenses into: fixed bills (same each month), variable needs (change month to month), and discretionary spending (optional).
- Identify “non-monthly” expenses: car repairs, annual fees, gifts, back-to-school costs, subscriptions billed yearly.
If you’re unsure about paycheck withholding, the IRS Tax Withholding Estimator can help you spot whether your take-home pay might change during the year.
Choose a budgeting method that matches real life
The best method is the one you’ll follow weekly—not the one with the fanciest spreadsheet. Pick a structure that fits your income and your stress level.
Budgeting methods at a glance
| Method | Best for | How it works | Common pitfall | Quick fix |
|---|---|---|---|---|
| 50/30/20 | Beginners with steady pay | Needs/Wants/Savings split | Needs category gets overloaded | Track needs separately (housing, food, transport) to spot the real driver |
| Zero-based | Debt payoff or tight cash flow | Assign every dollar a job | Feels restrictive if too detailed | Use broader categories and adjust weekly |
| Priority-first | Variable income | Fund essentials first, then goals | Savings gets skipped in lean weeks | Create a baseline savings “minimum” and automate it |
Build your categories (and make room for the “unknowns”)
Most budgets fail because they ignore the predictable surprises—expenses that aren’t monthly, but always happen.
- Start with core categories: housing, utilities, food, transportation, insurance, minimum debt payments.
- Add easy-to-forget categories: medical, personal care, kids/pets, household supplies.
- Create “sinking funds” for irregular expenses (example: $50/month for car maintenance, $30/month for gifts).
- Add a buffer line for the first month. Even $25–$100 can prevent a single overspend from turning into a chain reaction.
For budgeting education tools and printable planning ideas, the Consumer Financial Protection Bureau (CFPB) budgeting resources are a helpful reference.
Use worksheets to turn plans into a repeatable routine
Worksheets work because they make decisions visible. Instead of wondering where your money went, you can see what you planned, what happened, and what to change next week.
- Use a monthly overview sheet to set category limits and list bills by due date.
- Use a weekly check-in sheet to reconcile spending, see what remains, and adjust before you run out.
- Use a bill tracker to reduce late fees and decision fatigue.
- Keep a notes area for one-time events (birthdays, travel, school fees) so next month is easier.
Real-life budgeting: handle irregular income, surprises, and overspending
If your income changes month to month
Build your plan from a conservative baseline (your lowest typical month). Treat extra income as choices: catch-up bills, sinking funds, savings, and debt—rather than letting it disappear into “extra spending.”
When a surprise expense hits
Use a simple order of operations: pause discretionary categories first, then reduce variable needs, and adjust savings last. This helps you avoid defaulting to credit when the issue is really a temporary cash-flow squeeze.
When a category keeps getting blown up
Use “if-then” rules to reduce decision fatigue
A simple weekly process that keeps the budget working
If you want a structured learning path alongside your budget, the FDIC Money Smart program offers practical financial education materials.
When the basics are stable: level up your plan
A guided option with built-in worksheets and practical examples
- Master Your Money: The Ultimate Guide to Creating a Budget That Works (with Worksheets & Real-Life Tips) | How to Budget Money Worksheet eBook for Beginners
- The Ultimate Employee Motivation Checklist: Spark Your Team’s Drive in 7 Easy Steps! | Books on How to Motivate Employees | Printable PDF Download | Workplace Culture Guide
FAQ
What is the easiest budgeting method for beginners?
The 50/30/20 method is often the simplest starting point if income is steady, while a basic zero-based budget works well when money is tight. Whichever you choose, a weekly check-in is what makes it stick and keeps limits realistic.
How do budgeting worksheets help compared with using an app?
Worksheets make your plan visible and intentional—especially for bill due dates, sinking funds, and category limits. Many people use them alongside apps to create a clear weekly routine instead of relying on notifications alone.
How can a budget work with irregular income?
Start with a conservative baseline month, cover essentials first, and keep a small buffer category. When extra income arrives, assign it intentionally to catch-up bills, sinking funds, savings, and debt instead of letting it drift into unplanned spending.




Leave a comment